Will BNPL or Online Betting Impact Your Mortgage Application?
Better Loan Solutions in Mornington Peninsula • Learning Centre • Insights
Better Loan Solutions in Mornington Peninsula • Learning Centre • Insights
When applying for a mortgage, lenders scrutinise your financial habits to assess your creditworthiness.
Gambling activities, such as online betting, or using ‘buy now, pay later’ (BNPL) can potentially impact you negatively in the eyes of a
lender.
With our in-house mortgage broking division we bridge the gap between the countless phone calls and
emails between lender and accountant making your refinancing and borrowing much less stressful.
Gambling
Lenders view regular gambling, even small amounts, as a red flag. Online betting platforms in particular are closely scrutinised.
To improve your application, consider pausing or significantly reducing gambling activities for at least 3-6 months before applying.
Buy Now, Pay Later (BNPL)
While BNPL services may seem harmless, they can impact your borrowing capacity quite significantly.
To strengthen your application, consider reducing or eliminating BNPL and any associated accounts. Ahead of applying for a mortgage, it’s important to take stock and have a good hard look at the way you are spending your money.
Lenders want to see that you are a responsible spender with the means to pay them back. They want to see that you can save money, manage debts well and not spend more than you earn.
A great place to start is to talk to a mortgage broker who can sit down with you and look at your current
financial habits and see where you can improve.
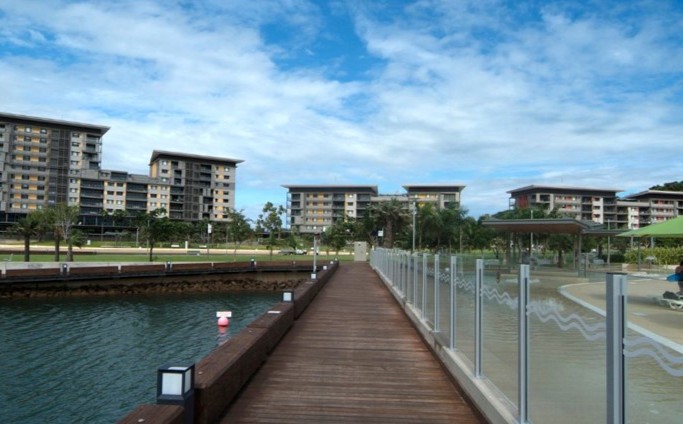
Darwin has become Australia's standout property market, recording house price growth of around 16 per cent and unit price growth of around 13 per cent
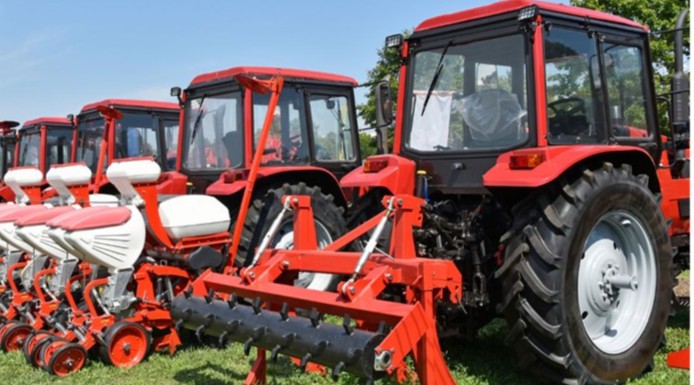
The start of a new financial year is an ideal moment to review your existing equipment finance commitments.
The auction environment is deliberately designed to create competition and momentum. Bidding can move quickly, and it is easy to get caught up in the heat of the moment.
Understanding this before you apply helps set realistic expectations and makes it easier to compare what different lenders are offering you rather than what they advertise.
Financing an older vehicle is a common goal, but it comes with a set of challenges that do not apply in the same way to newer cars.

Spring is consistently the busiest period of the year for Australian property, with more listings, open homes and competition than at any other time.
Since the beginning of 2025, 62 per cent of occupiers leasing more than 1,000 square metres have either expanded or maintained their footprint.
Darwin's commercial property sector is strengthening with rising rents.
On 26 June 2026, the Federal Government passed a significant change to how Self-Managed Super Funds (SMSFs) can invest in residential property. New Limited Recourse Borrowing Arrangements (LRBAs) to purchase residential property inside an SMSF will be banned from approximately 10 August 2026 — 45 days after Royal Assent.